The UnDrain: Stop the Leak, Start Your Financial Cushion
Your Move Today: Place $5–$20 into a dedicated emergency fund or savings jar.
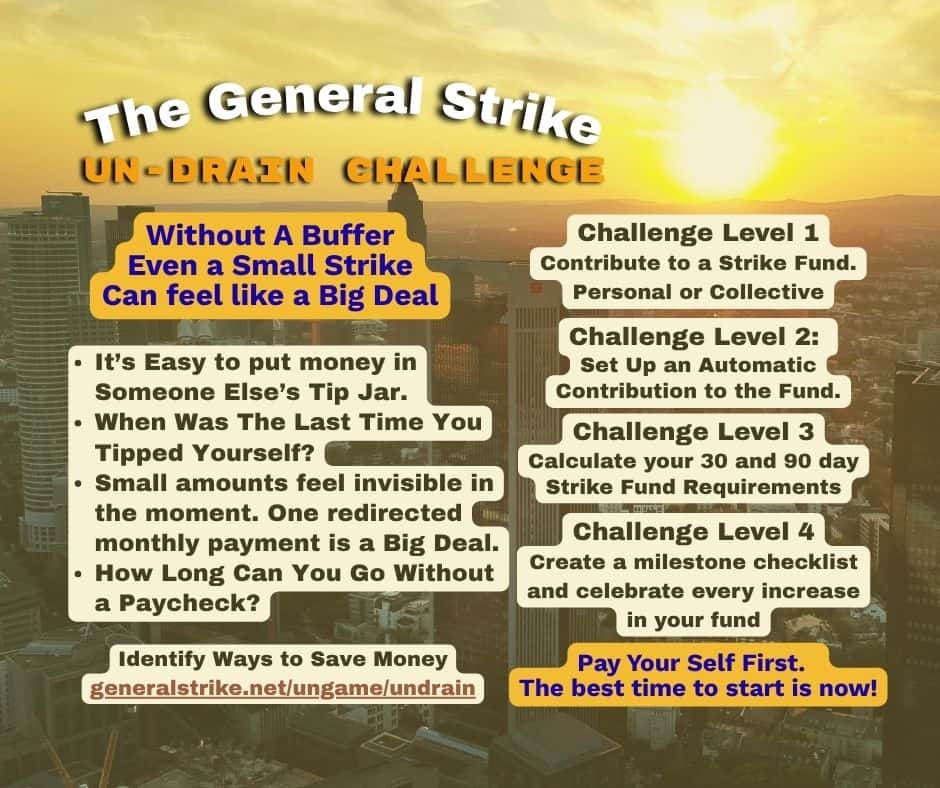
Have you noticed how easy it is to put money in someone else’s tip jar? When was the last time you put money in your tip jar?
Money doesn’t only disappear in large, obvious ways. Often, it drains quietly through numerous insignificant micro-expenses. A few dollars here, a quick purchase there. Each one seems harmless, but over time, they leave very little behind.
When there’s no buffer, even small disruptions feel bigger than they should: an unexpected bill, a slow week, a delayed payment. Without a cushion, these moments create stress that lingers long into the night.
Today’s move begins to change that pattern.
Small amounts feel invisible in the moment.
A quick convenience purchase. A small upgrade. A minor add-on at checkout. These decisions rarely feel significant enough to question.
Over time, these small outflows create a pattern where money continuously moves outward, but very little is retained.
Many people don’t consciously decide to live without a buffer. It simply happens as a result of consistent, low-friction spending combined with the absence of a deliberate saving habit. That’s what the experts say. We all know that for all too many of us that the money runs out long before the end of the month.
Gamemaster note: If this challenge seems impossible for you, we want you to know, we understand. We play this game collectively so, together, we can change this reality for everyone. Stick with us. We are going to win this thing, together.
Today’s Challenge
Place $5–$20 into an emergency fund.
This is not about the amount. It is about starting the habit of keeping something instead of spending everything.
Pay yourself first because you are worth it.
Do this so that you begin creating space between you and the next unexpected expense.
If this is something you thought about before, now might be the time to take this step.
Simple Directions Explained
Step 1: Choose where your savings will live.
This can be a physical jar, a separate savings account, or a dedicated space in your current account.
Step 2: Deposit $5–$20 today.
Choose an amount that feels easy to complete. The goal is consistency, not strain.
Step 3: Label it clearly.
Name it something personal like “Our Emergency Fund” or “My Financial Cushion” to reinforce its purpose and remind you who this money is for.
Step 4: Note the starting point.
Write down the amount and today’s date to mark the beginning.
Optional: Remove friction from saving.
If possible, separate this money from your main spending account so it is less likely to be used impulsively.
Extended Challenge
Level 2: Automate the habit.
Set up a small, consistent weekly transfer into your savings.
Level 3: Define your cushion.
Calculate what a 30-day, 90-day, and 180-day financial buffer would look like for your situation. This creates a clearer target and sense of direction.
Level 4: Build momentum.
Create a milestone checklist and acknowledge progress as you reach each level. If your financial cushion is already established, you may consider redirecting additional funds to support others, such as contributing to a local strike fund or a mutual aid effort.
Adapt these steps to fit your reality. You know your circumstances best.
Why This Matters
This isn’t just saving money. We are reducing financial fragility.
Many modern financial systems quietly assume that most people operate with little to no buffer. That assumption allows systems to function smoothly, but it also means individuals bear more of the risk when things change.
When there is no cushion, small disruptions become larger problems.
When a cushion exists, even in small amounts, it changes how decisions are made. Time expands. Options increase. Stress reduces.
We do this so that we can respond to life with intention rather than urgency.
Structural Impact
Financial systems are designed to function smoothly when money continues to flow.
Regular spending, predictable bill payments, and minimal savings buffers create a steady and reliable economic rhythm. This predictability supports lending models, consumer financing systems, and ongoing consumption patterns.
We are dependent, in part, because systems were designed for continuous participation. When money flows out as quickly as it comes in, individuals remain more exposed to disruption.
In this environment, operating without a cushion gas become normal.for too many of us.
This challenge introduces a different pattern.
Setting aside even a small amount interrupts the expectation that all available money will be spent. It begins to shift participation from automatic outflow toward intentional retention.
This is not about withdrawing from the system entirely.
Sudden financial disengagement without preparation can create instability and unintended consequences. A lack of liquidity at both the individual and system level can lead to stress, disruption, and imbalance.
Instead, this is a form of strategic redesign.
We are not blowing up the system. We are redesigning how we participate in it.
By building personal financial buffers, we create:
- More stability in moments of uncertainty
- Greater leverage in decision-making
- More freedom to choose rather than react
Over time, as more individuals build financial resilience, systems begin to adjust to participants who are less fragile and more intentional.
This is how small, consistent actions contribute to long-term structural change.
A Note of Reflection
Consider what it feels like to keep even a small portion of your money rather than spending it immediately.
Does this shift your sense of control, even slightly?
Before today, how often did money pass through your hands without anything staying behind?
And what might change over time if something did stay the same?
If you set aside even a few dollars today, you have already changed the pattern. You are no longer only participating in spending. You are participating in building.
Most people intend to save later. You started now.
That is how stability begins, one small decision at a time.
One move at a time, you are working your way across the Un-Game board, building awareness that leads to control.
Helpful Tools
NerdWallet Emergency Fund Calculator
Calculate your emergency fund target
This tool helps you estimate how much savings you may need based on your monthly expenses, giving you a clear and personalized target to work toward.
Consumer Financial Protection Bureau (CFPB)
How to build an emergency fund
This guide provides practical, step-by-step strategies for starting and growing savings, with focus on small, consistent actions that build long-term stability.
FDIC Savings Guide (Money Smart Program)
Tips for building savings and financial security
This resource offers foundational financial education, including how savings accounts work, how to protect your money, and how to build habits that support financial resilience.
USA.gov Financial Preparedness Resources
https://www.usa.gov/financial-preparedness
This government resource outlines practical steps to prepare financially for unexpected events, helping you build a basic safety net and make informed decisions during disruptions. Unfortunately this resource is no longer available